Knowing what a menu item costs to make is the first step toward pricing it deliberately. The arithmetic is straightforward; the details that often get missed are usable yield, portion size, small add-ons, packaging, and the invoice price you actually paid. This worked example uses an illustrative breakfast sandwich batch of 10. All prices and yields below are invented for demonstration, not supplier quotes or recommended market prices.
Use the latest supplier invoice for each item and keep units consistent. A repeatable receiving routine helps catch substitutions, quantity differences, and price changes before they flow into your recipe sheet.
1. Start with a defined recipe and batch yield
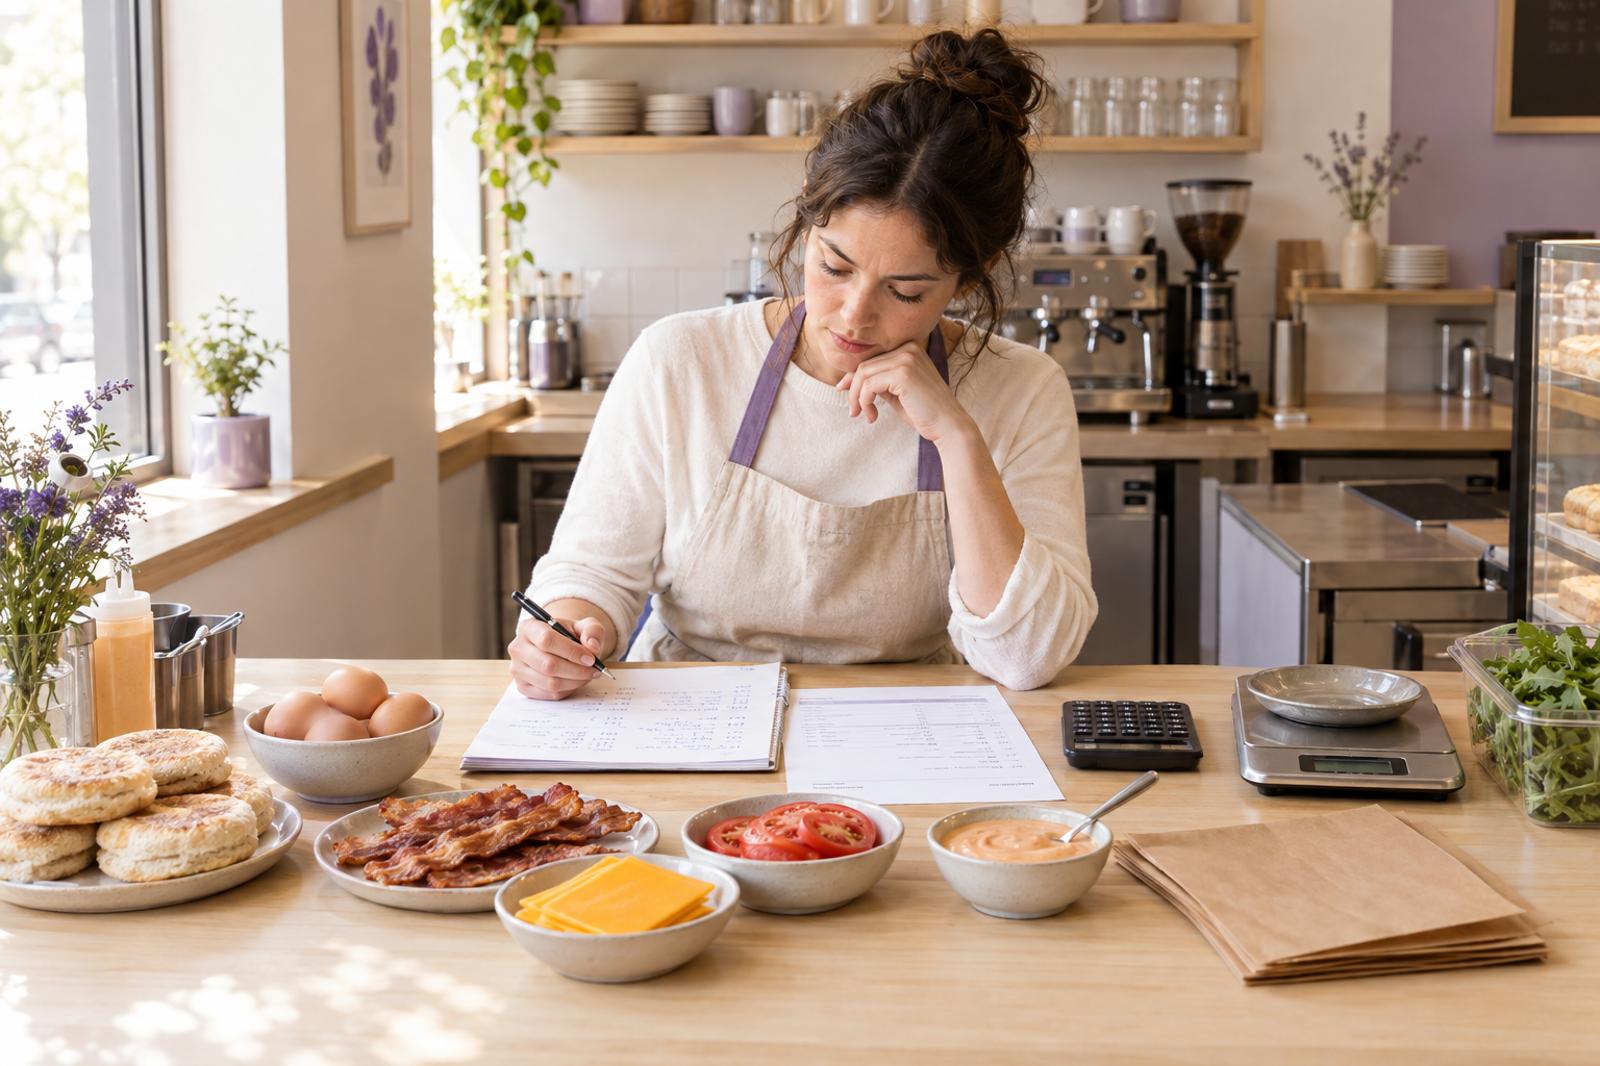
Assume the standard sandwich uses one English muffin, one egg, one ounce of cheddar, one ounce of cooked bacon, one ounce of prepared tomato, one measured sauce portion, and one paper sleeve. The batch makes 10 saleable sandwiches. If your actual portion is two bacon strips or a different tomato amount, cost that exact standard instead.
Record each ingredient in the form it is used. For items that lose weight through trimming or cooking, measure the usable yield in your kitchen. Yield is edible portion (EP) weight divided by as-purchased (AP) weight. For example, 5 pounds of raw bacon is 80 AP ounces; if cooking leaves 56 usable ounces, the measured yield is 56 ÷ 80 = 70%.
The USDA Food Buying Guide explains AP and EP quantities and shows how a yield factor changes the amount to purchase; its produce example is a helpful reference for the method, not a substitute for measuring your own ingredients. See USDA’s AP/EP yield example.
2. Convert invoice prices into usable-unit costs
For an ingredient with yield below 100%, divide its AP cost per unit by the yield expressed as a decimal: EP cost per unit = AP cost per unit ÷ yield. In the bacon example, $24 ÷ 80 AP ounces = $0.30 per AP ounce; $0.30 ÷ 0.70 = about $0.4286 per cooked EP ounce. Ten sandwiches need 10 EP ounces, so the bacon line costs about $4.29—not $3.00, which would ignore cooking loss.
For tomato, assume a 5-pound case costs $6 and a kitchen test shows 90% usable yield after trimming. Five pounds is 80 ounces, so AP cost is $6 ÷ 80 = $0.075 per ounce; EP cost is $0.075 ÷ 0.90 = about $0.0833 per usable ounce. At one EP ounce per sandwich, the 10-serving batch uses 10 ounces and costs about $0.83. Actual yield varies by produce, cut, supplier, and preparation; measure it rather than treating 90% as a universal figure.
3. Copy-ready costing worksheet: illustrative batch of 10
Use this list as a worksheet format. “Invoice basis” is the package price and size; EP cost is used when yield is below 100%. Quantities and all prices are illustrative.
- English muffins: $4.80 per 12; $0.40 each; 100% usable; 10 each per batch; line cost $4.00.
- Eggs: $9.00 per 30; $0.30 each; 100% usable; 10 each per batch; line cost $3.00.
- Cheddar: $8.00 per 32-ounce block; $0.25 per ounce; 100% usable; 10 EP ounces per batch; line cost $2.50.
- Bacon: $24.00 per 80 AP ounces; $0.30 per AP ounce; 70% measured cooked yield; $0.4286 per EP ounce; 10 EP ounces per batch; line cost $4.29.
- Tomato: $6.00 per 80 AP ounces; $0.075 per AP ounce; 90% measured trimmed yield; $0.0833 per EP ounce; 10 EP ounces per batch; line cost $0.83.
- Sauce: $3.60 bottle makes 36 standardized portions; $0.10 per portion; 10 portions per batch; line cost $1.00.
- Paper sleeves: $8.00 per 100; $0.08 each; 10 per batch; line cost $0.80.
Batch total: $16.42 for 10 servings. Cost per portion: $16.42 ÷ 10 = $1.642, or about $1.64. For accuracy, retain unrounded line calculations in your sheet and round the final per-portion amount for display. Include any other item actually used—such as cooking oil, butter, seasoning, a garnish, or a napkin—and use the same unit and rounding method each time.
4. Calculate food-cost percentage and a target price
The basic formula is food-cost percentage = cost per portion ÷ menu selling price × 100. If you choose an illustrative target of 30%, the price implied by this example is $1.642 ÷ 0.30 = $5.47. A practical menu price of $5.50 gives $1.642 ÷ $5.50 = about 29.9%.
Here, the example’s portion cost includes the paper sleeve. Some operators track packaging separately from food cost. Choose a consistent definition for your own reports; if you exclude packaging from the food-cost numerator, keep it visible as a separate direct serving cost rather than losing it. Taxes, discounts, complimentary items, and delivery commissions may also need separate treatment in your pricing and reporting.
A target is a planning input, not a universal rule. The National Restaurant Association reported 2024 median food and non-alcohol beverage costs of 32.0% of sales for full-service respondents and 32.4% for limited-service respondents, based on data from more than 900 restaurant operators in its 2025 Restaurant Operations Data Abstract. Those broad operating medians are context, not a target for every café or a direct comparison to this single-item example (which includes packaging). Read the Association’s 2024 food-cost findings.
Ingredient cost is not the same as profit. Labor, rent, utilities, card fees, waste outside the recipe yield, and other operating expenses are not included in the sandwich’s $1.64 portion cost. A price that meets a chosen food-cost percentage does not, by itself, prove that the item is profitable or that the target suits your concept.
5. Re-cost after a supplier price increase
Now assume the 5-pound bacon case rises from $24.00 to $27.60, while its measured 70% yield and the recipe stay the same. The new AP cost is $27.60 ÷ 80 ounces = $0.345 per ounce; the EP cost is $0.345 ÷ 0.70 = about $0.4929 per cooked ounce. Ten EP ounces now cost about $4.93, a rise of roughly $0.64 per batch or $0.064 per sandwich.
The revised batch total is about $17.06, or $1.706 per portion. At the old $5.50 menu price, that is about 31.0% of the selling price. To return to a 30% target, the formula gives $1.706 ÷ 0.30 = about $5.69; if your menu uses ten-cent increments, $5.70 is a nearby practical price to evaluate. Before changing the menu, check the current invoice, portion control, yield, other ingredient costs, competitor context, and customer expectations. For customer-facing communication ideas, see these menu price increase wording examples.
6. A simple re-costing routine
- Keep the current standardized recipe, portion sizes, and batch yield together.
- After receiving a new invoice or substituting a product, update its package cost and unit conversion. Note the invoice date and supplier.
- Re-test yield when the product, cut, preparation method, or usable output changes; do not reuse a yield that no longer matches the kitchen process.
- Recalculate line costs, batch cost, cost per portion, and the chosen cost percentage whenever an ingredient price, portion, yield, or menu price changes.
- Schedule a recurring review—monthly is a useful starting routine for many small operators—and do an additional check after a material price or recipe change. Your own purchasing cadence and volatility should set the final interval.
Keeping menu versions, recipe quantities, purchases, and supplies organized makes the calculations easier to revisit; the holiday catering menu and purchasing guide covers that record-keeping workflow in a seasonal setting. Ququ Food is described as a workspace for menu products and recipes, recording purchases and sales, and reviewing food finances. The calculations in this guide are general costing advice; this is not a claim that Ququ automatically calculates recipe cost. Learn about Ququ.
Quick formula recap
- Yield %: usable EP quantity ÷ AP quantity × 100.
- EP unit cost: AP unit cost ÷ yield as a decimal.
- Batch cost: add the cost of every ingredient, garnish, and included serving supply used in the standard batch.
- Cost per portion: batch cost ÷ saleable portions.
- Food-cost %: portion cost ÷ menu price × 100.
- Price at target: portion cost ÷ target percentage as a decimal.
Use measured yields and current invoices, keep the accounting definition consistent, and treat benchmarks as context rather than instructions. Re-cost when the recipe, usable yield, supplier price, or portion changes so your menu decisions are based on the version you actually serve.