Damaged cartons, out-of-season goods and slow movers can turn a December 31 inventory count into a pile of judgment calls. The practical first step is to decide what happens to each item group—not to label everything “write-off” and remove it from the list. Record what is physically on hand, separate items by condition, choose a defensible next action, and keep evidence of what you did.
This guide is for U.S. small retailers, makers and stockroom owners preparing for the 2026 year-end count. It is an operations checklist, not tax advice: inventory methods and the tax treatment of markdowns, disposals and donations depend on your circumstances. If you already use an inventory method, do not change it just to obtain a year-end result; confirm accounting and tax treatment with a qualified professional.
1. Sort the problem stock before deciding
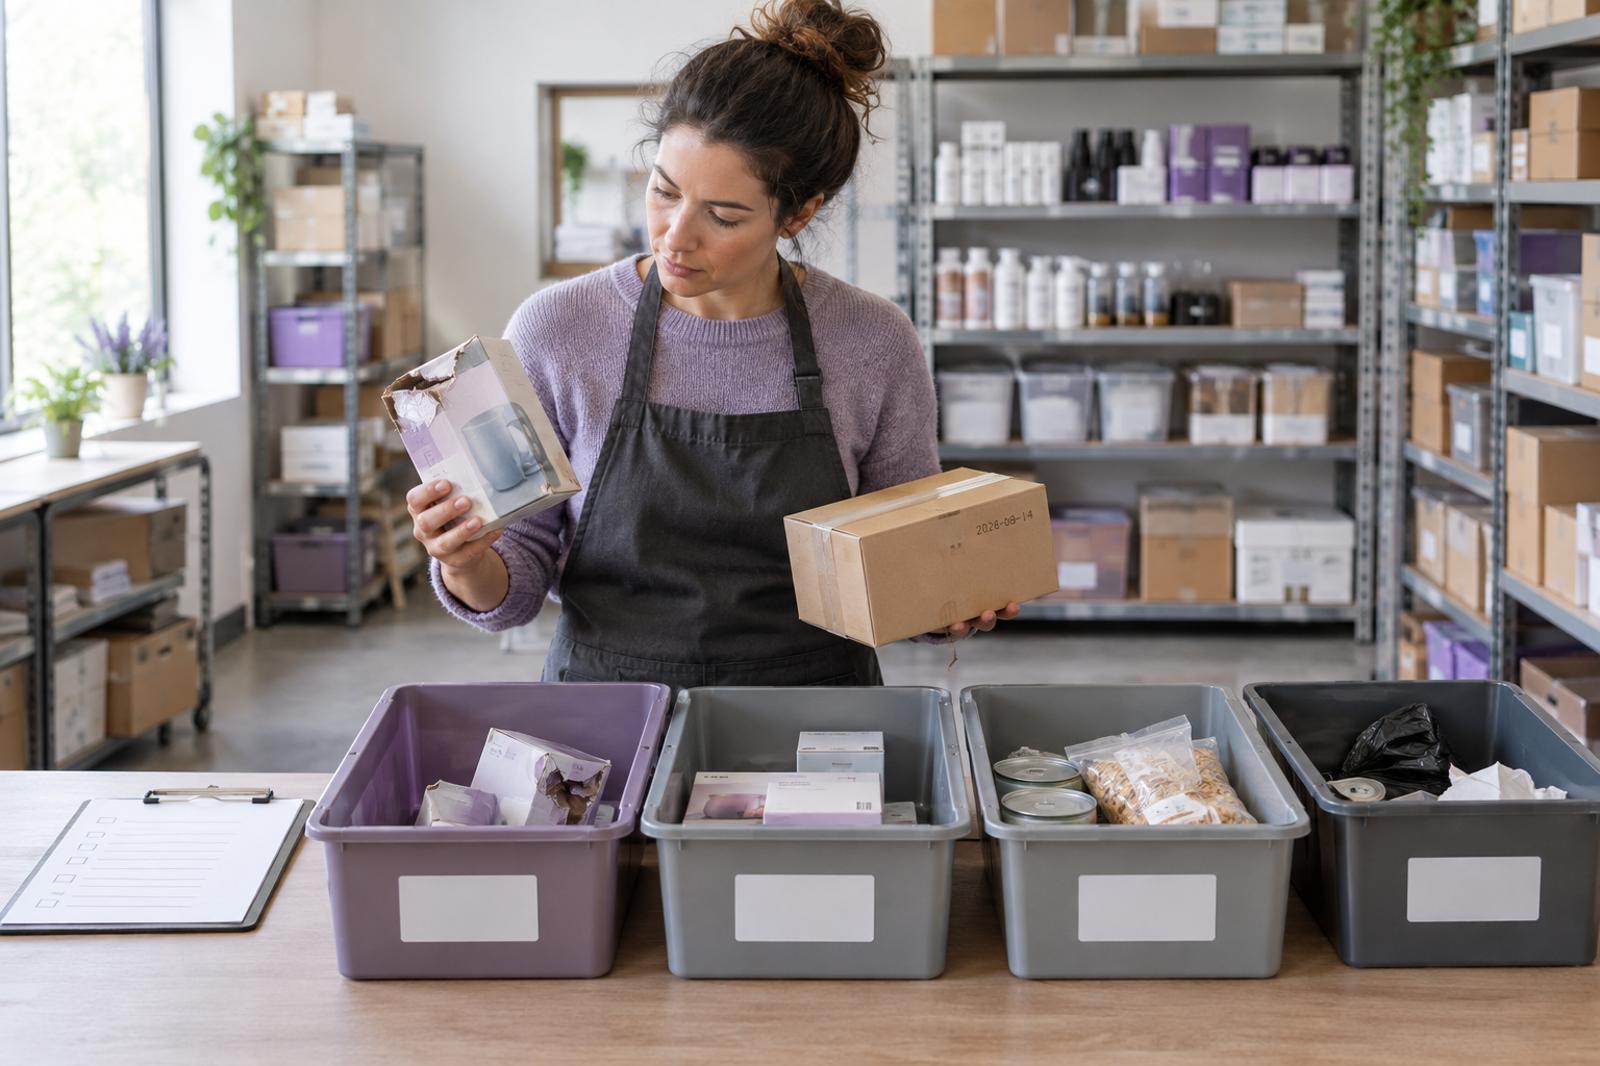
Move questionable items to a clearly identified review area and group them by condition. Keep the item, quantity, unit of measure and location visible so it can still be counted. Use categories that point toward an action:
- Damaged: crushed packaging, water exposure, broken pieces, shop wear or a defect that changes normal saleability.
- Expired or date-sensitive: past-date food, cosmetics, chemicals or other goods whose safe or lawful sale may be restricted. Follow applicable product and local rules; do not treat an unsafe item as markdown or donation stock.
- Obsolete or out of style: a discontinued model, seasonal design or product customers no longer want at the ordinary price.
- Odd lots or broken sets: incomplete packs, mismatched sizes, single components or quantities that no longer sell as a standard unit.
- Slow but still saleable: clean, complete goods with no safety concern that simply have not moved at the expected pace.
Photograph visibly damaged goods before handling or disposal. For a useful count workflow and cutoff controls, see the December 31 year-end inventory count checklist. For returned products that still need inspection, the holiday returns stockroom workflow can help connect intake checks to this disposition review.
2. Choose the next action item group by item group
Use this decision order, and document why the selected action makes sense. The figures below are invented examples for illustrating the workflow, not tax calculations or recommended price points.
- Return to the supplier when the contract or policy allows it. Ask for a return authorization, confirm the deadline, freight responsibility and credit amount, then retain the approval and shipping or credit evidence. Do not reduce the count until goods physically leave your control or your accountant confirms the correct cutoff treatment.
- Mark down and offer for sale when goods remain safe, complete enough to use and legally saleable. Set a real price, make the offer visible to the relevant customers, record when and where it ran, and retain a screenshot, dated sign, catalog or sales record. A markdown may be a commercial decision; it is not automatically a tax write-off.
- Bundle or rework when a damaged package, odd lot or incomplete set can still be sold honestly and safely. State what is included, avoid implying it is new or complete when it is not, and record any labor or repacking cost separately.
- Donate only if the recipient can use the goods and the items meet safety, quality and legal requirements. Confirm acceptance and obtain a dated receipt describing what and how much was transferred. Inventory donation deductions have special rules; do not assume the retail price or purchase cost is automatically deductible.
- Recycle or dispose when goods are unsafe, unusable or not worth returning or offering. Follow local requirements for food, chemicals, electronics and other regulated items. Keep a disposal receipt or a dated log with photos, quantities, reason and approver.
- Keep and review later if the stock is still saleable and the cost of a rushed clearance is greater than the expected benefit. Assign an owner and a specific review date rather than leaving “slow mover” as a permanent status.
Example: suppose a shop has 12 dented gift boxes that normally sell for $30 each. It may decide to offer the visibly imperfect boxes at $18 each and estimates $2 per unit in direct selling or disposition costs. The example produces an illustrative net offer amount of $16 per box; it does not determine the business’s inventory value or tax deduction. Preserve the actual offer and costs, then ask the tax professional how the rule applies to the business’s method.
3. Separate stockroom cleanup from tax valuation
The IRS’s Publication 538 explains that goods that cannot be sold at normal prices or used normally because of damage, imperfections, shop wear, style changes, odd or broken lots and similar causes may need special valuation. For qualifying goods, it describes valuation at bona fide selling price minus direct cost of disposition. That is a specific inventory valuation rule—not permission to write off every old, expired or slow-moving item at will.
The regulation adds an important evidence and timing detail. Under 26 CFR 1.471-2(c), a bona fide selling price means an actual offering during a period ending no later than 30 days after the inventory date. The taxpayer bears the burden of showing that the goods qualify and must keep disposition records that permit the inventory to be verified. For a December 31, 2026 inventory date, discuss the 30-day period—through January 30, 2027—with your tax professional. A plan to run a sale is not proof that the goods were actually offered; keep evidence of the offer and its dates.
Also distinguish a physical disposal from a valuation adjustment. Count goods that are still on hand at the inventory cutoff, even if they are damaged or have a planned return, donation or markdown. Record the later physical movement on its actual date; do not backdate a transfer or remove stock from the count merely because you intend to dispose of it. Your accountant can tell you how to present qualifying goods under your method and how a post-count sale or disposal affects the books.
Donation treatment is separate again. The IRS’s Publication 526 says the deduction for donated business inventory can depend on whether the property was included in opening inventory for the year and on its basis. A special enhanced food-inventory rule is conditional, not a general deduction for all businesses or every donation. For food, never donate unsafe or noncompliant items; check current food-safety rules and the receiving organization’s requirements before transfer.
Finally, not every small business is treated the same way for inventory accounting. IRS Publication 334 describes an exception for qualifying small-business taxpayers who choose not to keep inventory, while still requiring an accounting method that clearly reflects income. Whether you qualify and what records you need are fact-specific—confirm with your tax professional rather than assuming the year-end inventory rules do not apply.
4. Keep a disposition log that another person can verify
Use one line per item group, and attach supporting files rather than relying on a note that says only “written off.” A copy-ready log can use these fields:
Item/SKU and description | location | counted quantity and unit | condition and cause | normal price or cost reference | decision and reason | actual offer or transfer date | direct disposition costs | evidence file or link | approved by | final outcome/date
For a markdown, attach the dated public offer and final sales record. For a supplier return, attach the authorization, shipment confirmation and credit memo when received. For a donation, record the recipient, transfer date, quantities and receipt. For disposal, retain photographs or the service receipt and note why resale or return was not appropriate. If an item is kept, give it an owner and review date.
This documentation complements—but does not replace—source records such as purchase invoices, receiving documents or your accounting records. For the distinction between physical rotation and accounting valuation, see inventory valuation versus stock rotation. If your inventory list is being cleaned up at the same time, the photo-to-inventory intake checklist offers a separate verification workflow.
5. Run this five-day pre-count routine
- December 26 — Isolate and list. Set aside questionable stock, label the review area and start a group-level log. Keep saleable stock separate from unsafe or regulated goods.
- December 27 — Inspect and verify. Photograph damage, confirm item identity and units, count physical quantities, and note whether each group is still saleable. Ask another person to review high-value or disputed items.
- December 28 — Choose and authorize. Check supplier return windows, identify markdown candidates, confirm donation acceptance and local disposal requirements. Get approval for each action and identify any accounting question for the tax professional.
- December 29 — Complete actions that can be completed before cutoff. Make actual returns, transfers or sales where appropriate; retain dated evidence. Keep anything still on hand in the count area and log planned but incomplete actions.
- December 30 — Reconcile and prepare the count file. Check that every problem-stock group has a quantity, location, status, owner and evidence reference. Flag goods that remain physically present for inclusion in the December 31 count.
On December 31, count what is physically present under the same cutoff rules used for the rest of the stock. Record subsequent returns, markdown sales, donations and disposals on their actual dates. Do not rush an unsafe food or regulated-product decision to meet a bookkeeping deadline.
6. Use the decisions to prevent next year’s dead stock
After the count, tag each item group with a likely cause: over-ordering, optimistic seasonal demand, receiving damage, storage conditions, date rotation, incomplete sets or outdated product mix. Compare the cause with purchase quantities and sales history before changing reorder points. A damaged delivery points toward a receiving or packaging check; expiry points toward a smaller replenishment quantity or earlier rotation review; an obsolete style may call for a more conservative seasonal buy.
Ququ Warehouses is described for photo-based AI intake, bulk inventory edits and an organized warehouse list, which can help teams organize and update item records. It does not calculate tax valuation, determine write-offs, track donations or automatically decide stock adjustments. Explore Ququ if a clearer inventory list is part of your workflow, while keeping your accounting and disposition evidence in the appropriate records.
Bottom line: Count what you have, classify why it is a problem, choose a real next action and keep evidence for every movement or offer. Then ask a qualified tax professional how the facts fit your inventory method. That approach makes the year-end decision easier to explain—and gives next year’s purchasing and receiving process something concrete to improve.